Cisco stock closed at $115.34 on October 12, up about 55% this year. The rally has a clear engine. Hyperscaler orders for its AI networking gear jumped 4.5 times to $9.3 billion in fiscal 2026.
🔗Cisco Stock (CSCO): Q4 FY26 Earnings & the AI Bet
Traders read that as an AI hardware story. However, the more important story may run through Washington. The White House now treats trusted, American-built networks as a matter of national policy.
Only a small group of companies can build these networks at scale, and Cisco is among them.
This analysis separates the verified record from our forecast. It also examines what traders should watch before the November 11 earnings report.
The Numbers Behind Cisco Stock
Start with the latest quarter, because it set records. Cisco reported fourth-quarter fiscal revenue of $17.3 billion, an 18% increase from the previous year.
On a non-GAAP basis, the company earned $1.22 per share, beating expectations of $1.17. Meanwhile, public sector orders rose 30%. For the full fiscal year, revenue increased 12% to $63.3 billion.
🔗Earnings Per Share (EPS) Explained
Cisco Systems Q4 Fiscal 2026 Financial Results & Guidance
| Financial Item & Performance Metric | Q4 Fiscal 2026 Results & Guidance Figures |
|---|---|
| Total Quarterly Revenue | $17.3 billion (up 18% year-over-year) |
| Non-GAAP Earnings Per Share (EPS) | $1.22 per share (versus $1.17 consensus expected) |
| Public Sector Orders Growth | Up 30% year-over-year |
| Cybersecurity Revenue | $2.2 billion (up 14% year-over-year) |
| Hyperscaler AI Orders (Fiscal 2026) | $9.3 billion (4.5 times the prior fiscal year) |
| Fiscal 2027 Revenue Guidance Range | $72.2 billion to $73.4 billion |
The AI ramp continues to build. Fourth-quarter hyperscaler orders alone reached $4 billion. Furthermore, management expects approximately $7.5 billion in AI infrastructure revenue during fiscal 2027.
🔗AI Infrastructure Stocks: Power Players to Watch in 2026
Neocloud, sovereign, and enterprise customers contributed more than $1 billion in AI orders during the year. However, the warning sign appears in the margin outlook. Management guided gross margin to 65%–66%, below the fourth quarter’s 66.3%.
AI hardware typically carries thinner margins than software. Consequently, Cisco stock declined after investors examined the outlook, despite the earnings beat.
🔗How to Read an Earnings Report
Investment Takeaway: Growth is accelerating, but margins are moving in the opposite direction. Meanwhile, government demand remains a relatively stable component of the order book.
Washington’s Doctrine: Promote and Protect
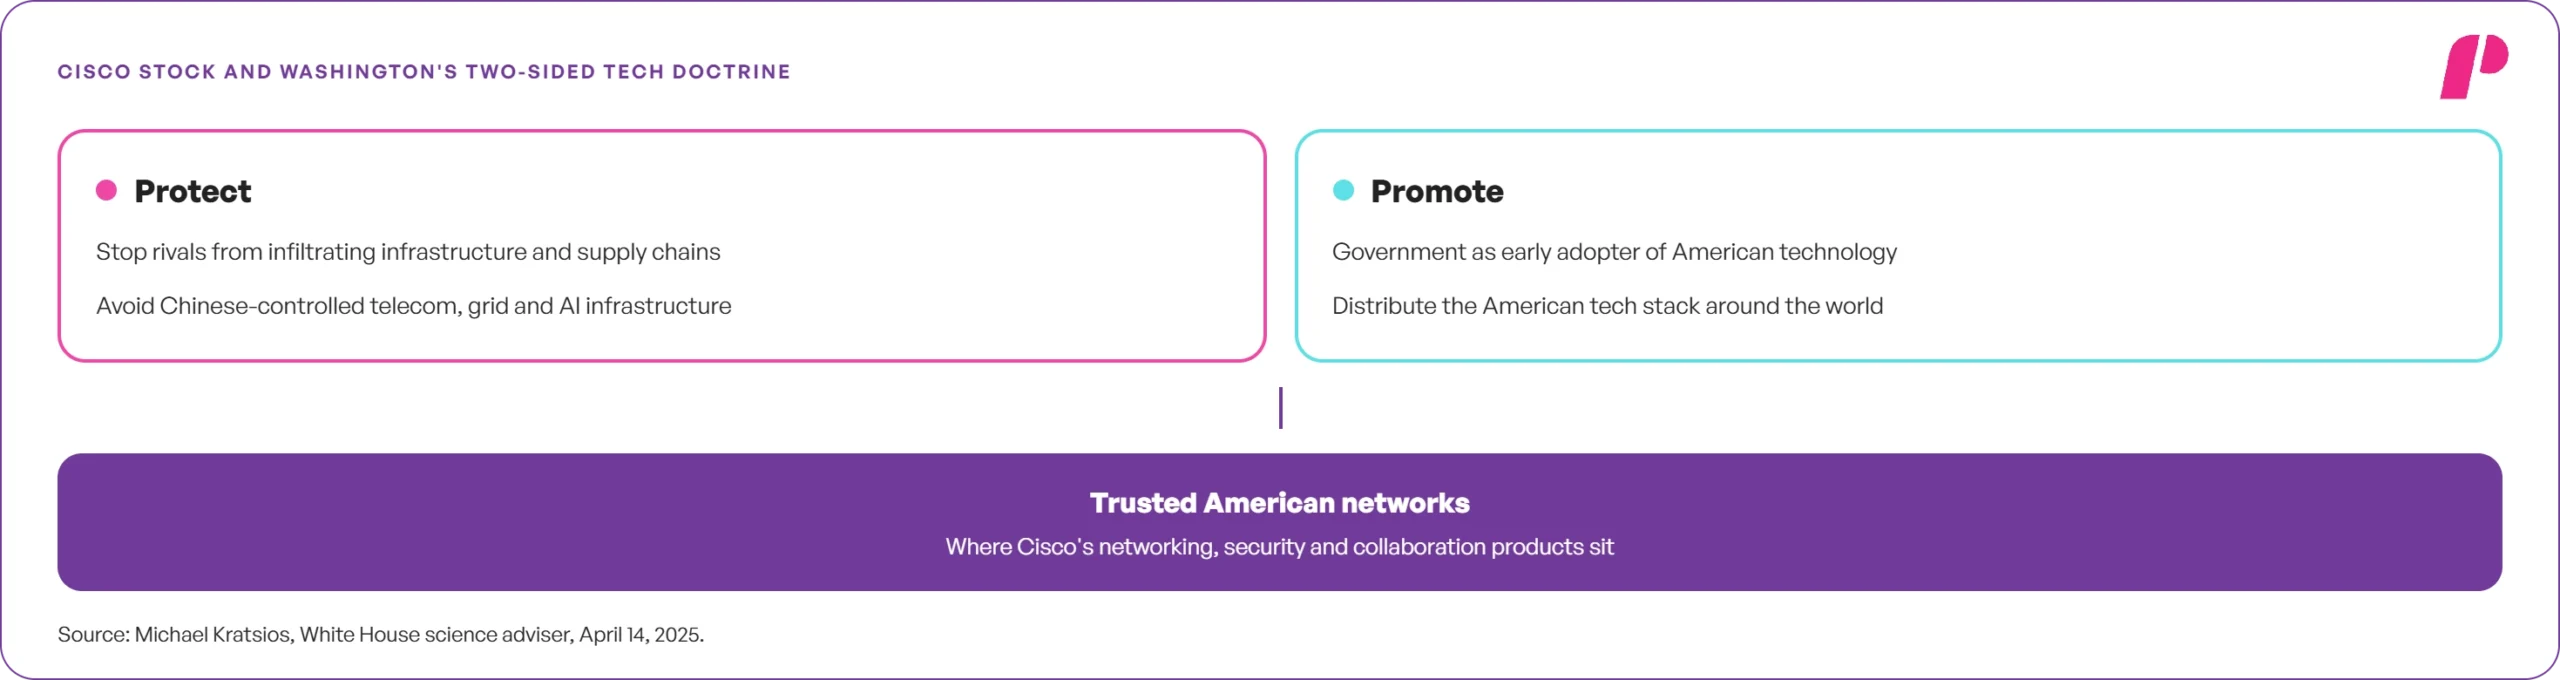
To understand why trusted networks matter, traders need to examine Washington’s technology policy. White House science adviser Michael Kratsios outlined the administration’s strategy on April 14, 2025.
He called for stopping rivals “from infiltrating our infrastructure and supply chains.” The adviser also warned against reliance on “Chinese-controlled critical infrastructure, whether in telecom, the grid, or AI.”
Furthermore, he urged the government to “become an early adopter and avid promoter of American technology.” That statement matters particularly for Cisco because it identifies federal purchasing as a potential growth channel.
🔗Sovereign AI Government Deals
Kratsios also encouraged American companies to “distribute the American tech stack around the world.” Cisco’s networking, security, and collaboration products represent an important part of that infrastructure.
🔗Intel Earnings Reports: The Intel SHIELD Contract Explained
Investment Takeaway: Trusted American technology has become an explicit policy priority. Consequently, Cisco’s position in critical networking infrastructure could support its long-term investment ca
Cisco Stock and the Genesis Mission Forecast
The policy took concrete form in November 2025. President Trump launched the Genesis Mission through an executive order on November 24, 2025.
The Energy Department operates the initiative as a national AI platform for scientific research. It connects supercomputers, quantum systems, and data across 17 national laboratories.
Its objectives include energy dominance and national security. Cisco appears among approximately 50 initial collaborators, alongside RTX, Dell, Hewlett Packard Enterprise, NVIDIA, Microsoft, and Quantinuum.
In December 2025, the department signed formal agreements with 24 organizations. NVIDIA subsequently confirmed that its agreement covers fusion energy and quantum computing.
🔗Nvidia Stock Analysis: Can NVDA Own AI, Robotics and Quantum?
Project Genesis Federal AI Mission
| Genesis Mission Parameter | Mission Detail & Operational Scope |
|---|---|
| Launch Authorization | Executive order (issued November 24, 2025) |
| Lead Federal Agency | U.S. Department of Energy (DOE) |
| Infrastructure Scope | 17 national laboratories, high-performance supercomputers, and quantum computing systems |
| Cisco Systems Participation Status | One of approximately 50 initial corporate collaborators |
| Formal Partnership Agreements | 24 participating organizations finalized in December 2025 |
| Architectural Design Rule | Mandate for architecture-agnostic technology products |
The verified record stops there. Neither Cisco nor the department has disclosed a contract value. Furthermore, Genesis products must remain “architecture-agnostic,” limiting vendor lock-in.
Our forecast goes further. In our view, Washington could select Cisco to develop a sealed communications layer protecting Genesis and classified research networks.
Such infrastructure would rely on verified American hardware and authenticated software. It could also isolate sensitive scientific workflows from foreign exploitation.
However, no agency has announced such a selection. Therefore, this remains an investment hypothesis rather than a confirmed development.
Investment Takeaway: Genesis already places Cisco within a strategic federal initiative. If the forecast materializes, government networking contracts could become another growth driver for Cisco stock.
Zero Trust Credentials the Pentagon Already Uses
Cisco’s defense role predates Genesis. The Pentagon’s Comply-to-Connect program evaluates devices before allowing them onto a network.
The system verifies identity, patch status, and compliance before segmenting access. Cisco markets its Identity Services Engine as a policy engine supporting this framework.
Meanwhile, Splunk, acquired for approximately $28 billion, provides additional security analytics across these networks.
🔗Cybersecurity Stocks Explained
Cisco’s collaboration products also have federal credentials. In August 2020, the NSA evaluated 17 collaboration services for government use. According to Cisco, Webex ranked best of breed, supported by end-to-end encryption and customer-held encryption keys.
Cisco Systems Defense & Enterprise Security Credentials
| Defense Credential & Security Parameter | Detail & Operational Implementation |
|---|---|
| DoD Comply-to-Connect Mandate | Cisco markets Identity Services Engine (ISE) as the primary access policy engine |
| Enterprise Security Analytics | Splunk integration (acquired for approximately $28 billion) |
| NSA Collaboration Guidance (2020) | Cisco documentation notes Webex ranked as best-of-breed |
| Data Encryption Standard | End-to-end encryption supported with customer-held encryption keys |
| Aerospace & Space Deployment | Webex flew on NASA’s Artemis I mission during the Callisto technology demonstration |
Cisco’s reach also extends to space and remote installations. In 2022, Webex traveled aboard Orion during NASA’s Artemis I mission.
The technology formed part of the Callisto demonstration, developed with Lockheed Martin and Amazon. Additionally, Cisco SD-WAN can use Starlink satellite connectivity to support communications at remote locations.
🔗Iran Drone Threat: Best Defense Stocks 2026
Investment Takeaway: Public sector orders increased 30% during the latest quarter. Government relationships can support recurring demand, although future revenue still depends on procurement decisions and contract renewals.
The Advisory and Board Layer
Influence in Washington also operates through advisory relationships. CISA’s roster of the President’s National Security Telecommunications Advisory Committee includes Cisco chief operating officer Maria Martinez.
However, Cisco does not hold an exclusive position. Broadcom’s Hock Tan also serves on the committee, alongside executives from AT&T, Verizon, Lockheed Martin, and Amazon.
🔗Stock in Focus: Broadcom Stock (AVGO)
Therefore, participation signals industry relevance rather than a unique competitive advantage.
Cisco Systems Board of Directors
| Board Director Name & Title | Professional Background & Governance Expertise |
|---|---|
| Michael D. Capellas | Lead Independent Director; former Chief Executive Officer of Compaq Computer Corporation |
| Mark Garrett | Former Chief Financial Officer of Adobe Inc.; serves as Audit Committee Chair |
| Dr. Kristina M. Johnson | Former U.S. Under Secretary of Energy; former President of Ohio State University |
| John D. Harris II | Former Vice President of Business Development at Raytheon Company |
| Charles H. Robbins | Chair and Chief Executive Officer of Cisco Systems |
Kristina Johnson stands out because she previously oversaw Energy Department research programs, which now form the foundation of Genesis.
Similarly, John Harris brings defense-industry experience from Raytheon. Wesley Bush, formerly chief executive of Northrop Grumman, also served as a director until October 2025.
🔗RTX 2026: The $300 Billion Titan of Aerospace and Defense
In our view, Cisco’s board combines energy research and defense experience that aligns with federal priorities. This background could prove valuable if the Genesis forecast develops into commercial opportunities.
Investment Takeaway: Cisco’s leadership understands complex government procurement processes. Nevertheless, experience alone does not guarantee contracts or future revenue.
Quantum Networking: A Long-Term Opportunity for Cisco Stock
Quantum networking represents one of Cisco’s longer-term opportunities. Today’s quantum computers lack sufficient qubits to solve many practical problems.
Cisco aims to connect multiple quantum machines so they can operate as a larger system. However, quantum information cannot simply be copied between network nodes.
Instead, these networks distribute entanglement between distant locations. That shared entanglement enables quantum teleportation of information between machines.
🔗Quantum Leaps’ Impact on Microsoft Stock Price
Quantum Networking & Entanglement Milestones
| Quantum Research Milestone & Technical Description | Achievement Date / Timeline |
|---|---|
| Prototype Entanglement Chip (developed in collaboration with UC Santa Barbara) | May 2025 |
| Multi-Node Quantum Entanglement (transmitted over 17.6 km of New York fiber) | February 2026 |
| Universal Quantum Switch Prototype | April 2026 |
| Quantum Network Controller Research Prototype | October 2026 |
The prototype chip generates up to 200 million entangled photon pairs per second. Moreover, it operates over standard telecommunications fiber while consuming less than a milliwatt.
In April, Cisco reported that its switch transmitted 5,400 entangled pairs per hour across New York. According to the company, this represented approximately 10,000 times the performance of earlier experiments.
🔗QBTS Earnings Report Q1 2026: Bookings Surge, Revenue Miss
Investment Takeaway: Quantum networking may take years to contribute meaningfully to earnings. Nevertheless, the research positions Cisco to compete in the infrastructure supporting distributed quantum computing.
Optics and the Co-Packaged Future
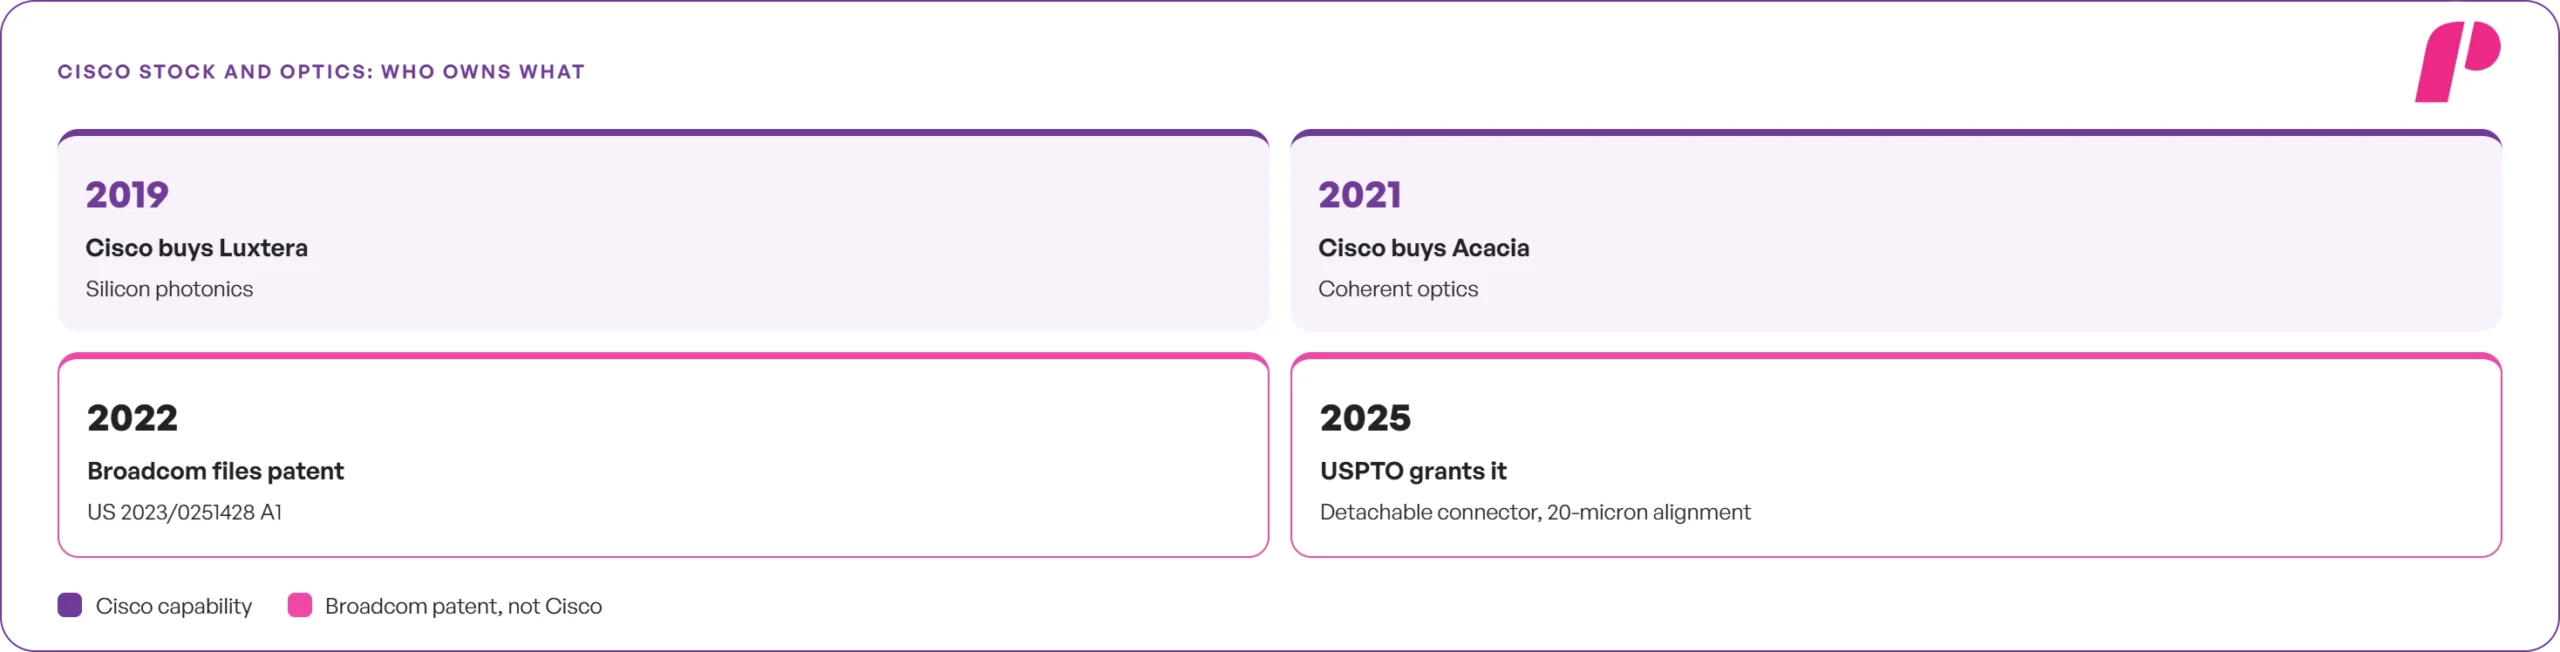
AI data centers are moving optical connections closer to switching chips. Cisco developed its photonics capabilities through acquisitions, beginning with Luxtera in 2019 and Acacia Communications in 2021.
As a result, the company produces its own silicon photonics and coherent optics. These capabilities become increasingly important as network speeds approach 1.6 terabits and beyond.
However, one distinction matters. Some analyses incorrectly credit Cisco with a key patent covering detachable co-packaged optics connectors.
Patent records instead identify Broadcom as the assignee of US 2023/0251428 A1. The filing describes a removable connector capable of maintaining alignment within 20 microns.
Broadcom engineers submitted the application in 2022, and the USPTO granted the patent in 2025. Therefore, the field-replaceable connector design belongs to Broadcom rather than Cisco.
🔗Broadcom Q3 2026 Earnings Preview: Can Patents Power a $100B AI Bet?
Cisco competes through integrated systems, software, and internally developed optical technology. Meanwhile, many hyperscaler deployments continue to rely heavily on Broadcom’s merchant switching silicon.
Investment Takeaway: Cisco has established optical networking capabilities, but it does not possess every patent advantage attributed to it. Ultimately, commercial execution will determine its competitive position.
The Key Risks Facing Cisco Stock
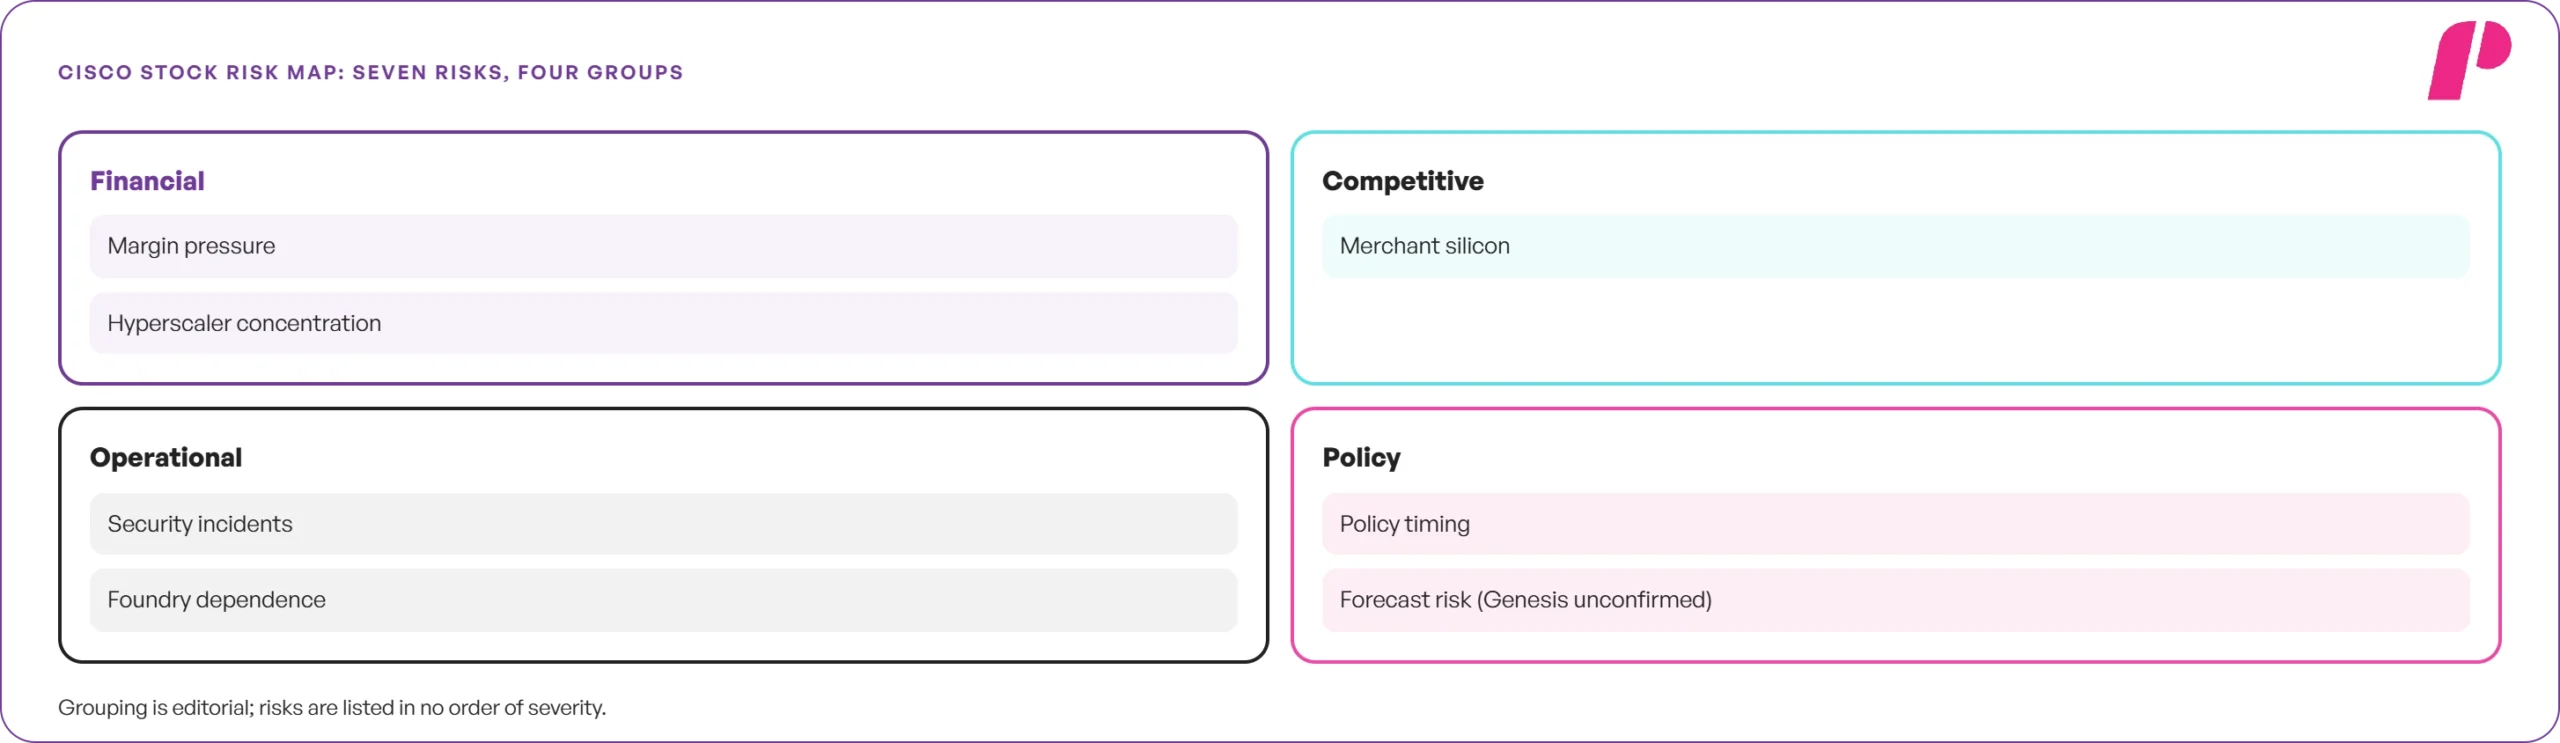
Despite its AI growth and government relationships, Cisco faces several risks that could affect future earnings and valuation.
- Margin Pressure: AI hardware is pulling expected gross margins toward 65%–66%.
- Hyperscaler Concentration: A relatively small number of major cloud providers account for much of the AI order volume.
- Merchant Silicon: Broadcom chips remain prominent in hyperscaler switching architectures.
- Security Incidents: In January 2026, attackers exploited a critical vulnerability affecting Cisco products.
- Foundry Dependence: Advanced semiconductor production relies on external manufacturers in Asia.
- Policy Timing: Federal programs remain exposed to budget reductions and changes in administration.
- Forecast Risk: The proposed Genesis networking opportunity remains unconfirmed.
🔗Risk Management in Stocks: A Complete Guide 2026
Together, these risks could influence Cisco stock even if demand for AI netwo
Trading Cisco Stock Around November 11
Cisco is scheduled to report first-quarter fiscal 2027 results on November 11. Analysts expect approximately $1.29 in earnings per share, while management has guided revenue to $18.0 billion–$18.2 billion.
To estimate a possible market reaction, traders can use a simple calculation:

🔗Options Expected Move Explained
For example, assume a hypothetical implied move of 5%. At a Cisco stock price of $115.34, the expected move would be approximately $5.77.
That produces an illustrative trading range of $109.57–$121.11. However, the 5% assumption should be replaced with the current options-implied figure before the announcement.
🔗Swing Trading Risk Management
Cisco Systems Equity Catalyst & Monitoring Framework
| Catalyst Signal & Metric | Where to Find / Data Source | Likely Effect on Cisco Stock Valuation |
|---|---|---|
| Gross Margin Guidance | Official quarterly earnings release | Serves as the primary swing factor for share price movement |
| Public Sector Orders | Quarterly earnings release & disclosures | Key performance gauge for federal and government demand |
| AI Revenue vs. $7.5 Billion Target | Earnings call transcripts & investor decks | Core metric that validates or tests the enterprise AI investment thesis |
| Genesis & Federal Contract News | Department of Energy (DOE) & Cisco press releases | Would strongly support institutional growth forecasts and public sector backlog |
| Exploited Vulnerability Advisories | Cisco PSIRT and CISA cybersecurity advisories | Generates short-term headline pressure and sentiment risk |
Investment Takeaway: Margins may matter more than revenue during this earnings cycle. Furthermore, confirmed federal contracts would provide stronger evidence supporting the defense investment thesis.
Valuing Cisco Stock
Cisco’s valuation reflects both its recent growth and investor expectations for AI infrastructure spending.
However, the central question is whether the market adequately recognizes its potential role in secure government networks.
Cisco Systems Valuation Markers & Peer Multiple Comparison
| Valuation Marker & Financial Metric | Figure & Peer Comparison Benchmarks |
|---|---|
| Share Price Close (October 12, 2026) | $115.34 per share |
| 52-Week Trading Range | $66.81 to $130.37 |
| Trailing Price-to-Earnings (P/E) Ratio | About 35.6x |
| Normalized P/E Ratio (Morningstar) | About 26.7x |
| Arista Networks Normalized P/E (Peer Benchmark) | About 61.0x |
| Palo Alto Networks Normalized P/E (Peer Benchmark) | About 105.4x |
| Average Wall Street Analyst Target | $136.16 per share |
Analysts remain divided. Citi maintains a Buy rating with a $139 target, while Bernstein values the shares at $110. Meanwhile, Piper Sandler reduced its target to $125.
🔗Analyst Price Targets Explained
Cisco also pays a quarterly dividend of $0.42, representing a yield near 1.5% at the referenced share price. Additionally, the company returned $3.2 billion to shareholders during the latest quarter.
Share repurchases averaged $111.53 per share, close to the October 12 closing price. Approximately $8.1 billion remains under the existing authorization.
🔗Stock Buybacks Explained
In our view, the market continues to value Cisco primarily as a cyclical hardware supplier. Consequently, its role in secure federal infrastructure may receive limited recognition in the current valuation.
🔗Cyclical Stocks in 2026: The Complete Prop Trader’s Guide
We expect a potential sovereign infrastructure premium to emerge if Washington’s strategic priorities translate into confirmed contracts.
Investment Takeaway: Cisco trades at lower earnings multiples than several technology peers. However, a sustained defense-related valuation premium would require visible federal contract wins.
Cisco Stock: Is Its Defense Potential Undervalued?
Cisco has assembled an unusual combination of capabilities. The company reported record revenue, while AI orders increased 4.5 times. Moreover, it participates in the Genesis Mission as an initial collaborator.
Its collaboration tools have established government credentials, and its quantum networking research continues to advance. At the same time, Washington’s technology strategy increasingly emphasizes the trusted American infrastructure Cisco supplies.
However, one important question remains unanswered. Will the federal government formally expand Cisco’s role in national security networking?
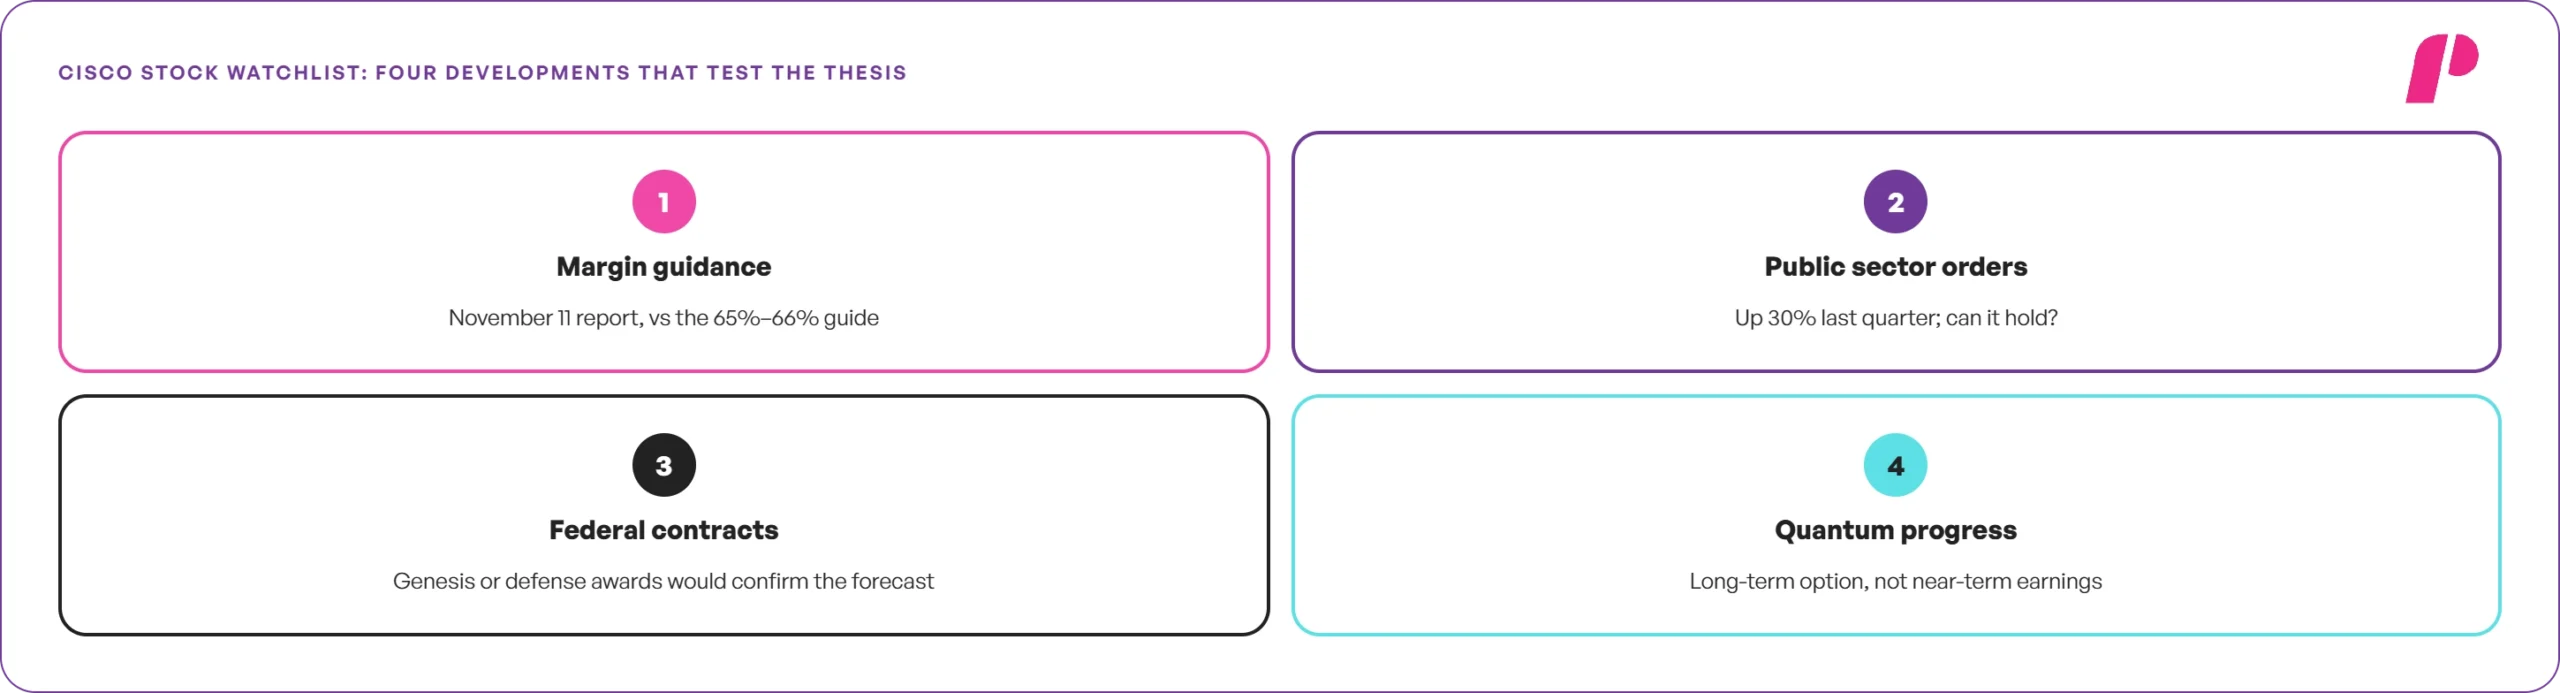
Four developments deserve attention: November 11 margin guidance, public sector orders, federal contract announcements, and quantum networking progress.
In our view, Cisco represents an important American defense networking asset. Nevertheless, whether Cisco stock is undervalued depends on how successfully these capabilities translate into sustainable earnings growth.
NFA. DYOR. This analysis is for informational purposes only and does not constitute investment advice. Forecasts represent the author’s views, and calculations are hypothetical illustrations.
If you liked this post make sure to share it!